
Free PRMIA 8006 Exam Practice Questions & Explanations
Prepared & Reviewed by the ValidExamDumps Editorial Team
At ValidExamDumps, we consistently monitor updates to the PRMIA 8006 exam questions by PRMIA. Whenever our team identifies changes in the exam questions, objectives, focus areas or requirements, We immediately update our exam questions for both PDF and online practice exams. This commitment ensures our customers always have access to the most current and accurate questions. By preparing with these up to date and 100% exam domain coverage questions, our customers can successfully pass the PRMIA Exam I: Finance Theory, Financial Instruments, Financial Markets – 2015 Edition exam on their first attempt without needing additional materials or study guides.
Other certification materials providers often include outdated or removed questions by PRMIA in their 8006 exam. These outdated questions lead to customers failing their PRMIA Exam I: Finance Theory, Financial Instruments, Financial Markets – 2015 Edition exam. In contrast, we ensure our questions bank includes only precise and up-to-date questions. Our main priority is your success in the PRMIA 8006 exam, not profiting from selling obsolete exam questions in PDF or Online Practice Test.
The LIBOR square swap offers the square of the interest rate change between contract inception and settlement date. If LIBOR at inception is y, and upon settlement is x, the contract pays (x - y)2 for x > y; and -(x - y)2 for x < y.
What of the following cannot be a value of the gamma of this contract?
The LIBOR square is a (rare) derivative contract which pays, as mentioned in the question, the square of the interest rate move between two dates. If LIBOR at inception is y, and upon settlement is x, the contract pays (x - y)^2 for x > y; and -(x - y)^2 for x < y.
For any question that involves calculating delta or gamma, and the payoff is described in terms of variables as is the case here, remember that delta is always the first derivative and gamma is the second derivative. For this question, let us calculate the second derivative and see what the gamma is:
If x > y, then the payoff is (x - y)^2
The first derivative wrt x is 2(x - y)
The second derivative wrt x is 2.
ie, the gamma is 2
If x < y, then the payoff is -(x - y)^2
The first derivative wrt x is -2(x - y)
The second derivative wrt x is -2.
ie, the gamma is -2
If x = y, then the payoff is 0. Both the first and the second derivatives are zero. ie the gamma is 0.
Based on the above, we see that the contract can have a gamma of either 0, +2 or -2. 1 is not a possible value for gamma, and therefore Choice 'b' is the correct answer.
According to the dividend discount model, if d be the dividend per share in perpetuity of a company and g its expected growth rate, what would the share price of the company be. 'r' is the discount rate.
A.

B.

C.
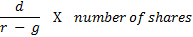
D.

According to the dividend discount model, the spot share prices represent the present value of all the future cash flows from the stock. If held till perpetuity, this becomes an annuity equal to the dividend, growing at its expected growth rate. Therefore Choice 'a' is the correct answer. Choice 'c' would represent the total market cap, and not the value per share that the question asks.
What would be the total all in price payable on an 5% annual coupon bond quoted at a clean price of $98, where the settlement date is 60 days after the latest coupon payment. Use Act/360 day basis.
The all in price would be equal to the clean price plus accrued interest. The accrued interest for the 60 days that have passed since the last coupon payment is $5 x 60/360 = $0.83. Therefore the dirty price, or the all in price, will be $98.83. (Note that the $5 is the annual 5% coupon on the $100 face.)
The relationship between covariance and correlation for two assets x and y is expressed by which of the following equations (wherecovarx,yis the covariance betweenxandy,xandyare the respective standard deviations andx,yis the correlation betweenxandy):
A)
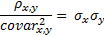
B)
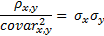
C)

D)
None of the above
Choice 'b' is the correct answer. The other relationships are not correct.
Using a single step binomial model, calculate the delta of a call option where future stock prices can take the values $102 and $98, and the call option payoff is $1 if the price goes up, and zero if the price goes down. Ignore interest.
To solve this question, we need to revisit how delta is calculated in a single step binomial model:
Consider a portfolio with just two positions: 1 Long Call option, and Short Stock. We do not know what (Delta) is.
Now if the current price of the stock is P, which can take the value P2 (higher value) and P1 (lower value) in the future at time T, then needs to be such that the value of the portfolio is equal in both the cases. If the price goes up, the value of the option will be $1 (given) and the value of the short stock will be - P2. If the price goes down, the value of the option will be $0, and the value of the stock will be - P1.
Therefore, $1 - P2 = $0 - P1.
Solving for , we get = $1 /(P2 - P1) = $1 / ($102-$98) = 1/4.