
Free AICPA CPA-Regulation Exam Practice Questions & Explanations
Prepared & Reviewed by the ValidExamDumps Editorial Team
At ValidExamDumps, we consistently monitor updates to the AICPA CPA-Regulation exam questions by AICPA. Whenever our team identifies changes in the exam questions, objectives, focus areas or requirements, We immediately update our exam questions for both PDF and online practice exams. This commitment ensures our customers always have access to the most current and accurate questions. By preparing with these up to date and 100% exam domain coverage questions, our customers can successfully pass the AICPA CPA Regulation exam on their first attempt without needing additional materials or study guides.
Other certification materials providers often include outdated or removed questions by AICPA in their CPA-Regulation exam. These outdated questions lead to customers failing their AICPA CPA Regulation exam. In contrast, we ensure our questions bank includes only precise and up-to-date questions. Our main priority is your success in the AICPA CPA-Regulation exam, not profiting from selling obsolete exam questions in PDF or Online Practice Test.
On December 31, 1989, a building owned by Pine Corp. was totally destroyed by fire. The building had fire insurance coverage up to $500,000. Other pertinent information as of December 31, 1989 follows:
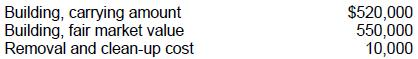
During January 1990, before the 1989 financial statements were issued, Pine received insurance proceeds of $500,000. On what amount should Pine base the determination of its loss on involuntary conversion?
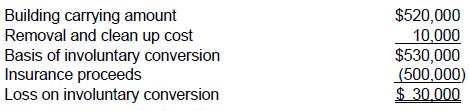
Choice 'b' is correct. $530,000 basis of involuntary converted building.
In which of the following situations may taxpayers file as married filing jointly?
RULE: In order to file a joint return, the parties must be MARRIED at the end of the year. Exception: If the parties are married but are LEGALLY SEPARATED under the laws of the state in which they reside, they cannot file a joint return (they will file either under the single or head of household filing status).
Choice 'a' is correct. Per the above rule, taxpayers who are married but lived apart during the year are allowed to file a joint return for the year. The fact that they did not live together during the year has no bearing on the issue.
Choice 'b' is incorrect. Per the above rule, taxpayers who are married but lived under a legal separation agreement at the end of the year may not file a joint return. They will generally file either under the single or head of household filing status.
Choice 'c' is incorrect. Per the above rule, taxpayers who were divorced during the year may not file a joint return together, as they are not married at the end of the year. [Note, however, that they may become married again in the year and file a joint return with the new spouse.]
Choice 'd' is incorrect. Per the above rule, taxpayers who were legally separated but lived together for the entire year may not file a joint return. They will generally file either under the single or head of household filing status.
Greller owns 100 shares of Arden Corp., a publicly-traded company, which Greller purchased on January 1, 2001, for $10,000. On January 1, 2003, Arden declared a 2-for-1 stock split when the fair market value (FMV) of the stock was $120 per share. Immediately following the split, the FMV of Arden stock was $62 per share. On February 1, 2003, Greller had his broker specifically sell the 100 shares of Arden stock received in the split when the FMV of the stock was $65 per share. What is the basis of the 100 shares of Arden sold?
Choice 'a' is correct. The receipt of a nontaxable stock dividend will require the shareholder to spread the basis of his original share over both the original shares and the new shares received resulting in the same total basis, but a lower basis per share of stock held. Therefore, Greller total basis remains the same, $10,000, but is now split between 200 shares (a 2-for-1 split and he originally owned 100 shares).
Therefore, his basis per share goes from $100/share ($10,000/100) to $50/share ($10,000/200).
Consequently, his basis in 100 share is 100 x $50 = $5,000.
Choices 'b', 'c', and 'd' are incorrect per the above Explanation: .
Which one of the following statements is correct with regard to an individual taxpayer who has elected to amortize the premium on a bond that yields taxable interest?
Choice 'c' is correct. The bond's basis is reduced by the amortization of the premium.
Choice 'a' is incorrect. For bonds acquired after 12/31/87, the amortization of the premium is an offset to interest income on the bond rather than a separate interest deduction.
Choice 'b' is incorrect. The amortization of the premium will reduce taxable income.
Choice 'd' is incorrect. The bond's basis will be decreased by the amortization.
The rule limiting the allowability of passive activity losses and credits applies to:
Choice 'c' is correct. The rule limiting the allowability of passive activity losses and credits applies to personal service corporations.
Choice 'a' is incorrect. The passive activity limitations apply to the various partners in the partnership as opposed to the partnership itself.
Choice 'b' is incorrect. The passive activity limitations apply to the various shareholders in the S corporation as opposed to the corporation itself.
Choice 'd' is incorrect. The passive activity rules do not apply to widely-held C corporations.
During 1993 Kay received interest income as follows:
On U.S. Treasury certificates $4,000
On refund of 1991 federal income tax 500
The total amount of interest subject to tax in Kay's 1993 tax return is:
Choice 'a' is correct. Interest income from U.S. obligations is generally taxable. Interest income on a federal tax refund is taxable, even though the refund itself is not taxed.
Choice 'b' is incorrect. Interest income on a federal tax refund is taxable, even though the refund itself is not taxed.
Choice 'c' is incorrect. Interest income from U.S. obligations is generally taxable.
Choice 'd' is incorrect. Interest income from U.S. obligations is generally taxable. Interest income on a federal tax refund is taxable, even though the refund itself is not taxed.
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994 Form 1040.
In 1994, Joan received $1,300 in unemployment compensation benefits. Her employer made a $100 contribution to the unemployment insurance fund on her behalf.
'F' is correct. $1,300. Unemployment compensation benefits are fully taxable (when received by the employee), but contributions made by the employer to the insurance fund are not taxable.
Mosh, a sole proprietor, uses the cash basis of accounting. At the beginning of the current year, accounts receivable were $25,000. During the year, Mosh collected $100,000 from customers. At the end of the year, accounts receivable were $15,000. What was Mosh's gross taxable income for the current year?
Choice 'c' is correct. The facts state that cash collections from customers were $100,000 and as a cash basis taxpayer this is the amount of Mosh's gross taxable income for the year. Note that according to the formula BASE - we can determine the amount of sales = $90,000, but that would give us accrual, not cash basis, income.
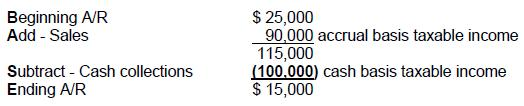
Choice 'a' is incorrect. See Explanation: above.
Choice 'b' is incorrect. $90,000 is the amount of sales that would be Mosh's taxable income if Mosh were an accrual basis taxpayer.
Choice 'd' is incorrect. See Explanation: above.