At ValidExamDumps, we consistently monitor updates to the AICPA CPA-Financial exam questions by AICPA. Whenever our team identifies changes in the exam questions, objectives, focus areas or requirements, We immediately update our exam questions for both PDF and online practice exams. This commitment ensures our customers always have access to the most current and accurate questions. By preparing with these up to date and 100% exam domain coverage questions, our customers can successfully pass the AICPA CPA Financial Accounting and Reporting exam on their first attempt without needing additional materials or study guides.
Other certification materials providers often include outdated or removed questions by AICPA in their CPA-Financial exam. These outdated questions lead to customers failing their AICPA CPA Financial Accounting and Reporting exam. In contrast, we ensure our questions bank includes only precise and up-to-date questions. Our main priority is your success in the AICPA CPA-Financial exam, not profiting from selling obsolete exam questions in PDF or Online Practice Test.
The following items were among those that were reported on Lee Co.'s income statement for the year ended December 31, 1989:
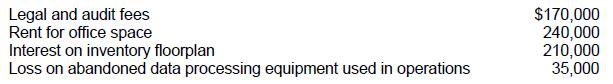
The office space is used equally by Lee's sales and accounting departments. What amount of the abovelisted items should be classified as general and administrative expenses in Lee's multiple-step income statement?
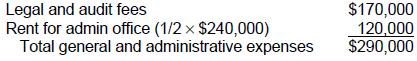
Note: 1/2 of the office space of $240,000 was used by the sales department, which should be allocated to 'selling expenses' (not general and administrative).
Choice 'a' is correct. $290,000.
Which of the following is correct concerning financial statement disclosure of accounting policies?
Choice 'b' is correct. Disclosure of accounting policies (and all other disclosure also) is an integral part of the financial statements.
Choice 'a' is incorrect. For disclosure of accounting policies, disclosure should not be limited to principles and methods peculiar to the industry in which the company operates. All material accounting policies should be disclosed.
Choice 'c' is incorrect. For disclosure of accounting policies, the format and location of accounting policies are not fixed by GAAP. Accounting policy disclosures are normally Note 1, but that is a (reasonable and very general) practice and not a 'rule.' It does make sense to disclose the 'why' before the 'what.'
Choice 'd' is incorrect. Disclosure of accounting policies should not duplicate details disclosed elsewhere in the financial statements.
Interim Financial Reporting
Reclassification adjustments must be shown in the financial statement that discloses comprehensive income:
Choice 'c' is correct. Reclassification entries may be necessary to avoid double counting an item previously reported as comprehensive income (i.e., unrealized gain), which are now reported as part of net income (i.e., realized gain).
Choice 'a' is incorrect. The classification of assets as current or non-current has no bearing on reporting comprehensive income.
Choice 'b' is incorrect. All items of comprehensive income must be shown net of the related tax effects, but it is not done with reclassification adjustments.
Choice 'd' is incorrect. Transactions with shareholders such as paying dividends and issuing capital stock are not included in comprehensive income, thus, reclassification adjustments are not necessary to exclude them.
Goddard has used the FIFO method of inventory valuation since it began operations in 1987. Goddard decided to change to the weighted-average method for determining inventory costs at the beginning of 1990. The following schedule shows year-end inventory balances under the FIFO and weighted-average methods:
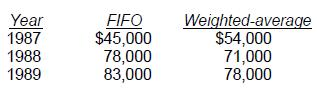
What amount, before income taxes, should be reported in the 1990 retained earnings statement as the cumulative effect of the change in accounting principle?
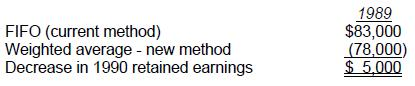
Choice 'a' is correct. $5,000 decrease.
The cumulative effect of change in accounting principle is determined as of the beginning of the year of change if comparative financial statements are not presented. In this case, the year of change is 1990, so the cumulative effect is the difference in inventory as of the end of 1989. [Note that inventory is a balance sheet item, so the change is based on the balances at the end of the last year the prior method was used. Had this question shown annual income statement amounts of cost of goods sold, we would have had to look at all the past years in the aggregate.] This will allow us to arrive at the adjustment to obtain the amount of retained earnings that would have been reported at the beginning of the period of change if the new accounting principle had been used for all prior periods.
How should the effect of a change in accounting estimate be accounted for?
Choice 'd' is correct, a 'change in accounting estimate' affects only the current and subsequent (future) periods, if the change affects both. It does not affect 'prior periods,' nor 'retained earnings.'
Choice 'a' is incorrect. Restating prior years' financial statements is required when comparative financial statements are shown for prior period adjustments of 'corrections of errors,' 'changes in entities,' and changes in accounting principle.
Choices 'b' and 'c' are incorrect. A 'change in accounting estimate' does not affect prior periods.

